
Law firm accounting carries compliance obligations that standard small-business bookkeeping simply doesn’t. The gap between the two is where most firms get into trouble. Trust account mismanagement, IOLTA violations, and cash-flow blind spots don’t usually start with negligence.
They start with a system that was never set up correctly for legal work.
According to the 8 am/MyCase 2024 Legal Industry Report, more than one in ten lawyers cite accounting as the most challenging function their firm faces, which explains why these mistakes are common enough to name specifically.
Every issue covered here may already exist in your books. The goal is to find it before a bar audit or client dispute does.
Treating Law Firm Accounting Like Standard Small-Business Bookkeeping
Law firm accounting follows different rules than standard small-business bookkeeping, and that distinction is where most compliance problems begin.
The small-business habit that doesn’t transfer to legal work
A typical small-business accounting system treats money coming in as revenue. But law firms don’t work that way. Not all the money flowing through the bank accounts of a law firm belongs to the firm yet.
A two-attorney firm receives a $10,000 retainer and records it as revenue on day one. Over the following six weeks, $4,000 worth of work is completed and billed against it. The remaining $6,000 still belongs to the client, but the books show the full $10,000 as firm income. The profit and loss statement looks strong. The owner draws against it. Then the client disengages and requests the unused balance back. The firm can’t produce it cleanly because it was never tracked separately. That single miscategorization created both a compliance exposure and a financial position that was never real.
This creates two problems: a risk of mishandling client funds, and a profit picture that looks stronger than it actually is.
The fix is to divide the money into two different categories: earned fees and unearned fees.
This is why human judgment still matters in legal financial decisions. Software can recognize transactions, but a person still needs to decide whether a payment has been earned based on the work done on the case.
4 core terms you need before anything else
Before correcting any of the mistakes below, these four terms form the foundation of accounting for law firms, and getting them wrong is usually where the trouble starts:
- Trust account: A separate bank account holding client funds the firm has not yet earned. This money belongs to the client, not the firm, until specific work is completed.
- Operating account: The firm’s own money, i.e., earned fees, paid expenses, and business funds. Nothing from the trust account belongs here until it has been earned.
- Earned vs. unearned fees: Earned fees are revenue; work has been completed and billed. Unearned fees are a liability, money received for work not yet done. The distinction determines which account the funds belong in.
- Fee agreement: The document that defines when fees are considered earned. Without a clear fee agreement, the line between earned and unearned becomes a judgment call, and judgment calls create compliance risk.
Trust Accounting Mistakes That Put Your Bar License at Risk
Trust accounting mistakes can have serious consequences for law firms. Even a small bookkeeping error can lead to compliance issues, financial losses, and a bar complaint.
Why trust and operating funds must stay separate
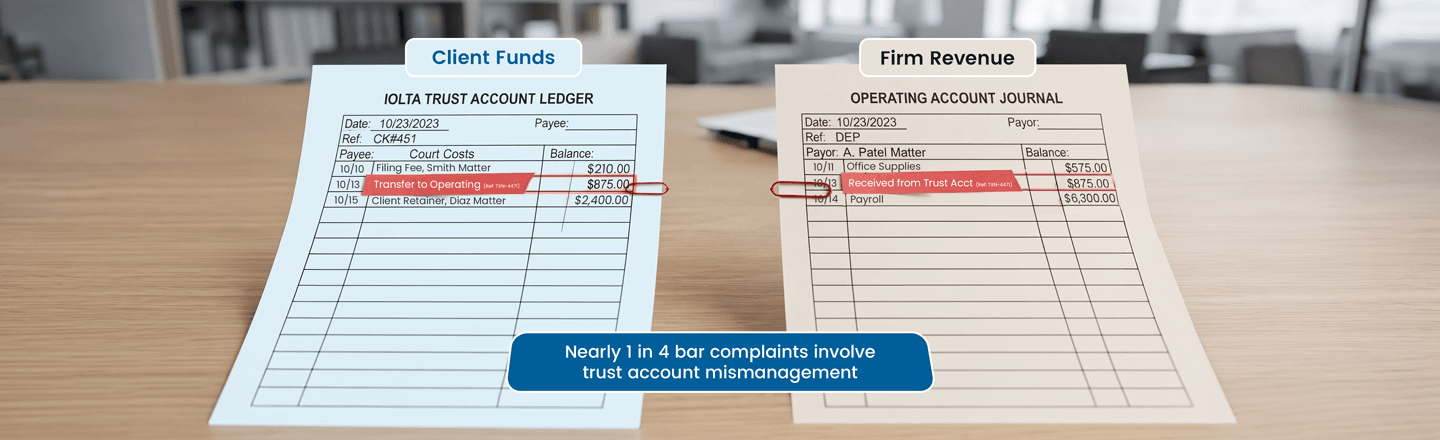
One of the most serious mistakes a law firm can make is using money from a trust account to pay the firm’s expenses, even temporarily, with the intention of replacing the money the same week.
It doesn’t matter how quickly it gets corrected. Using client funds for operating expenses is commingling, and it can trigger a bar investigation regardless of the intent. ABA Model Rule 1.15 establishes lawyers’ responsibilities for safeguarding client property, although specific trust-account requirements can vary by jurisdiction.
Here is what that looks like in practice: your bank statement shows $42,000 in the trust account. Your internal ledger also shows $42,000. Seems good, right? But when you add up the individual client balances, they only total $39,500. That $2,500 gap is the problem. It won’t surface in a bank balance check. It only appears in the three-way reconciliation, and finding it internally now is the difference between a quiet correction and a bar complaint.
Common causes of a mismatch include data entry errors, missed transfers, or a fee that was earned but never moved to the operating account. None of these will create issues if caught monthly. But it can become serious if they accumulate and remain undetected.
Three-way trust account reconciliation basics
A three-way trust account reconciliation means checking three records monthly:
- The trust account bank statement
- The firm’s internal trust account records
- The individual client balances recorded in the trust account
If all three don’t match, there is some issue. The issues can be a data entry error, or a missed transfer. This check is crucial before it becomes a major concern and shows up in a bar audit or a client dispute.
Law firms should complete this three-way reconciliation every month instead of just checking the bank balance. It helps law firms provide accurate trust account records when required.
Common IOLTA violations and their consequences
IOLTA, Interest on Lawyers’ Trust Accounts, is the most commonyl stem from four mistakes: commingling client and operating funds, failing to reconcile monthly, collecting a fee before it has been earned, and failing to track individual client balances within the trust account.
The consequences are not dependent on the size of the mistake. A bookkeeping error, if undetected for three months produce same bar complaint as deliberate misappropriation. The bar’s investigation looks at the records, not just the intent.
In 2023, nearly one-fourth of complaints investigated by the State Bar of California involved the handling of client trust account funds, according to its annual disciplinary report.
Depending on jurisdiction and severity, consequences can include mandatory restitution, suspension, or disbarment.
A practice built over fifteen years can be ended by trust accounting mistakes that started as administrative oversights.
State rule variations to verify
Law firms that operate in multiple states should not assume that trust accounting rules are the same everywhere. Requirements for reconciliation, handling interest, and reporting violations can vary by state.
California, for example, requires attorneys to comply with the Client Trust Account Protection Program (CTAPP). It mandates specific trust account disclosures and certifications. A firm licensed in another state that opens a California matter cannot assume its existing trust accounting setup meets CTAPP requirements.
The safest approach you can follow is to check trust accounting rules of each state where your law firms operate. Do not rely on rules from another state or information from a colleague, as those requirements may not apply to your firm.
The Cash vs. Accrual Mistake That Distorts Your Financial Picture
Choosing the right accounting method is crucial for law firms. It reflects how a firm records income and how its financial position appears.
The ABA’s cash-basis recommendation
When a law firm chooses the wrong accounting method, it prevents the law firm from seeing its actual financial position.
Cash-basis accounting records income when it’s actually received and expenses when they are actually paid.
Accrual-basis accounting records income when it is earned and expenses when they are incurred, even if the money has not yet been received or paid. This difference matters because it determines whether your records show unbilled work or only money already collected.
Signs a firm should move to accrual
A law firm may need to move to accrual accounting if:
- Unbilled work is growing, but nothing in the financial reports reflects it; the P&L looks flat even though attorneys are busy
- Monthly revenue swings by more than 20–25% without a clear change in case volume, usually a sign that cash timing, not actual performance, is driving the numbers
- The firm is scaling beyond two or three attorneys, and partners need visibility into work completed versus cash collected to make staffing or expansion decisions.
Switching accounting methods mid-year without consulting an accountant first is a common mistake. Changing from cash to accrual affects how income is reported for tax purposes and can create reporting inconsistencies that take significant time to untangle. Make the switch at the start of a fiscal year, with professional guidance.
Bookkeeping System Mistakes That Compound Silently Over Time
Unlike a trust accounting violation, a bookkeeping mistake may not cause an immediate problem. Instead, small errors can build up over time and make your financial records inaccurate.
A chart of accounts built for legal work
A common mistake that law firms make is using a generic chart of accounts, like using a default setup in QuickBooks or similar software, without adapting it for legal work.
Bookkeeping for law firms requires a chart of accounts that separates at minimum:
- Client trust liability: what the firm owes clients currently held in trust
- Operating income by fee type: flat fee, hourly, and contingency recorded separately
- Client cost advances: expenses paid on a client’s behalf, which are not firm
- Overhead and operating costs: rent, payroll, software, and other firm expenses
Reconciliation cadence and ownership
A second mistake is letting bookkeeping pile up for a full quarter. Delays in reconciliation make it harder to identify errors.
In a trust account context, a three-month-old discrepancy is significantly harder to explain than one caught in the same month it occurred.
The fix is to assign a specific person and a specific date to monthly reconciliation. A firm that schedules reconciliation for the fifth of every month, with one named owner, closes its books consistently. But a firm that leaves it as a shared responsibility closes it when someone gets around to it.
A separate risk arises when the same person handles both bookkeeping and check-signing with no second reviewer. In a small firm, this feels like efficiency, but it’s actually a control gap. Separating these responsibilities reduces the risk of both undetected errors and fraud.
For firms weighing how to structure this, comparing the true cost of a virtual hire versus an in-house employee is a practical starting point.
Recordkeeping and document retention
Document retention rules typically require firms to keep specific financial records such as trust ledgers, reconciliations, fee agreements, and billing records for a specific number of years. The retention periods vary from state to state.
This matters because a bar audit or client dispute may require firms to provide these records quickly. Good recordkeeping makes this process easier, while poor records can force a firm to spend time reconstructing missing information.
Reporting Mistakes That Hide Problems Until It’s Too Late
A law firm can have clean bookkeeping and still miss a cash flow problem simply because it doesn’t review financial information regularly.
Reading a P&L and balance sheet as a non-accountant
The most common reporting mistake is judging firm health by the bank balance alone.
Two reports give a clearer picture:
The profit and loss statement (P&L) shows income earned and expenses paid over a specific period. If revenue looks strong but the owner feels cash-strapped, the P&L shows where the gap is, whether it’s high overhead, slow collections, or both.
The balance sheet shows what the firm owns and owes at a specific point in time. Accounts receivable on the balance sheet shows money billed but not yet collected, a number the bank balance never reflects.
For firms looking to act on what those numbers reveal, these steps to improve law firm cash flow are a practical next step.
Collection rate and realization rate
Two metrics tell a law firm what it is actually keeping versus what it is doing:
- Realization rate measures how much of completed work actually gets billed. If an attorney works 40 hours on a matter but only 32 hours appear on the invoice, the realization rate for that matter is 80%.
- Collection rate measures how much of billed work actually gets paid. If the firm invoices $50,000 in a month and collects $41,000, the collection rate is 82%. The remaining $18,000 is either outstanding or at risk of being written off.
Tracking both monthly shows where the revenue leak is happening, befor before billing, after billing, or both.
Reviewing the same numbers every month
The most common and damaging financial mistake is reviewing the same numbers once a year at tax time.
Review these four numbers every month: cash position, collection rate, realization rate, and accounts receivable.
Regular reviews can help your law firm spot cash-flow problems before they become serious.
According to Clio’s Legal Trends Report, firms typically take about 32 days to collect outstanding invoices, and approximately 7% of invoices are never collected. For a firm billing $500,000 annually, that 7% represents $35,000 in revenue that disappears without a monthly review process to catch it early.
The same four numbers are required to be reviewed on the same data, every month.
The Profit-Killing Mistakes Most Firms Never Notice
Some mistakes don’t show up as a dramatic error, but they can quietly cost a law firm money every month.
Mistakes that create compliance risk
Law firms make a mistake when they hire a bookkeeper with no legal accounting background. Standard bookkeeping skills cover income, expenses, and reconciliation. They don’t cover trust account management, IOLTA requirements, or the distinction between earned and unearned fees.
Commingling client funds with operating funds is another serious risk. It can happen due to unclear account setups, incorrect transfers, or spending funds even before earning them. Law firms can reduce this risk by keeping client and operating funds strictly separate and performing monthly reconciliations.
Mistakes that hide lost revenue
A common mistake is writing off an under-billed matter and not noticing it during a monthly review. Regular billing review can help firms catch missing hours before an invoice is sent and recover the revenue.
A firm that reviews billing monthly catches billing gaps and protects its revenue. On the other hand, a firm that reviews billing at year-end may be too late to correct the missed charges.
If your firm is looking to close these types of gaps, you can follow proven strategies to improve law firm profitability, beyond accounting fixes.
The Mistake of Waiting Too Long to Get Help
The final mistake is waiting until tax season or an audit notice to seek outside accounting help instead of addressing potential problems early.
Signs a firm has outgrown DIY bookkeeping
A law firm has likely outgrown DIY bookkeeping when any of the following are true:
- The owner is doing bookkeeping on nights and weekends instead of billing that time to clients. Even at a modest hourly rate, the opportunity cost exceeds what outsourced support would cost
- Reconciliations are completed late or skipped entirely because nobody has clear ownership of the task
- Nobody in the firm can state the current collection rate or trust account balance without pulling up multiple documents
- The firm has received a bar inquiry, client complaint, or audit notice related to financial records
The first three signs mean the system has been outgrown. The fourth means the delay has already created risk.
Comparing the real cost of each option
The real cost comparison between DIY bookkeeping, an in-house hire, and outsourced accounting support is more than just the price.
DIY bookkeeping takes the owner’s valuable time. An in-house employee adds salary, benefits, payroll taxes, and training costs. For a part-time hire, the cost is lower, but the coverage gaps are common. In trust accounting, such a gap is a compliance gap.
Outsourced bookkeeping and accounting is a middle option where dedicated expertise without full-time employment costs can be rendered.
You can compare these options based on time saved, errors avoided, and overall value to get the best option for the law firm.
Making the transition without losing continuity
A five-attorney firm making this transition doesn’t need to overhaul everything at once. The most practical starting point is moving the monthly close, reconciliations, trust account tracking, and financial reporting to a dedicated remote bookkeeping and accounting team while the owner focuses on billable work.
Outsourced bookkeeping handles the monthly close, a virtual CPA assistant handles taxes and periodic reviews, and the owner reviews four numbers on a fixed date each month.
This clear division of responsibilities helps prevent accounting mistakes from building up again.
For firms dealing with overdue accounts, the instinct is often to turn to automated collection tools at times. However, automation consistently falls short on the accounts that require judgment and direct communication.
Understanding why human specialists outperform AI in recovering overdue accounts can help firms make the right call before choosing a collection approach.
Law Firm Accounting Mistakes Checklist
Use this checklist to identify accounting gaps in your firm before they become compliance problems:
- Trust and operating funds are kept in separate accounts.
- Client trust balances are tracked separately for each client.
- Three-way trust account reconciliation is completed monthly.
- Earned fees are transferred out of the trust account promptly.
- The firm has a legal-specific chart of accounts.
- Cash or accrual accounting is used appropriately for the firm.
- Accounts receivable and collection rates are reviewed monthly.
- Billing and realization rates are monitored regularly.
- Financial records and trust documentation are retained according to applicable state requirements.
- Bookkeeping and check-signing responsibilities are separated where practical.
- The firm reviews state-specific trust accounting and IOLTA requirements.
- The firm has a process for addressing accounting errors before they become compliance problems.
Conclusion
Every mistake covered in this article shares one trait: it compounds quietly. Trust violations don’t announce themselves until a bar audit surfaces them. Cash-flow gaps stay hidden until a slow month exposes what the bank balance was masking. Billing errors go unnoticed until year-end, when the revenue is already gone.
The firms that avoid these outcomes aren’t larger or better-resourced; they’re the ones that built the right system before the pressure hit. Separate accounts, monthly reconciliations, the right metrics reviewed on a fixed schedule, and accounting support that understands legal work specifically.
That is exactly what Remote Scouts is built for. Every firm Remote Scouts supports gets dedicated virtual bookkeeping assistants designed around the specific demands of legal practice: trust account management, three-way reconciliations, IOLTA compliance, and monthly financial reporting that gives firm owners a clear picture.
Most Frequently Asked Questions
Is leaving earned fees in trust for a few days after billing actually a violation?
Yes. Technically, it’s a violation. Leaving earned fees in a trust account after they have been billed creates commingling issues and can violate ABA Model Rule 1.15 regardless of how short the delay was.
The exact requirements vary by jurisdiction, but the principle is consistent: once a fee is earned, it belongs in the operating account, not the trust account. If this has already happened, document the timeline, reconcile the account, and check your state bar rules before making any corrective transfers.
Can one bookkeeper handle both my law firm and a separate business I own?
The bigger concern is whether your bookkeeper has legal accounting experience specifically. Someone skilled in general bookkeeping may not know the trust accounting and IOLTA rules that apply to a law firm. So, a mistake made from unfamiliarity carries the same consequences as one made deliberately.
How do I find out if my firm is on cash or accrual accounting without asking my accountant?
Pull up your most recent profit and loss statement. If it shows only money that has actually been received and expenses that have actually been paid, you are on cash basis accounting. If it also shows unbilled work in progress and outstanding payables before any money has changed hands, you are on accrual or a hybrid method.
This is worth confirming with your accountant before assuming either way, because switching methods mid-year has tax implications that are easier to avoid than to untangle later.
What is the first thing to check if my firm has not reconciled its accounts in months?
Start with the trust account before anything else. Pull the last bank statement and compare it against your internal trust ledger and individual client balances. If those three numbers do not match, that is your most urgent problem, and it needs to be resolved before you address anything else.
For the operating account, check whether your bank statements from the past three months have been reconciled in your accounting software. Unreconciled months, missing transactions, or balances that do not match are all signs of how deep the backlog runs. Bring that assessment to whoever you hire to fix it


